New legislation, noteworthy transactions and news from the firms themselves. One email a week; unsubscribe from any issue.
China Desk
China’s Chalco and Rio Tinto agree to acquire control of CBA for USD 900 million in one of Brazil’s largest mining deals
China’s Chalco and Rio Tinto agree to acquire 68.6% of Companhia Brasileira de Alumínio for 4.69 billion reais, with advice from international firms and approval from Brazil’s competition regulator
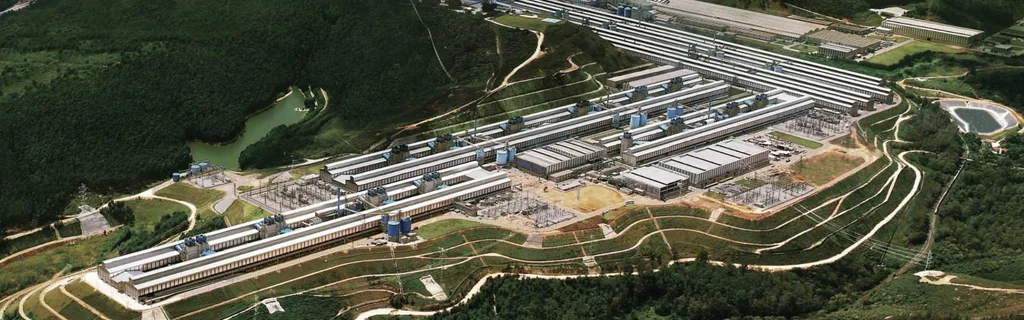
Aerial view of Companhia Brasileira de Alumínio (CBA)’s facilities in Brazil, where Chalco and Rio Tinto agreed to acquire a 68.6% controlling stake
Aluminum Corporation of China Limited (Chalco), a listed company belonging to the Chinese group Chinalco, and mining multinational Rio Tinto signed an agreement to acquire Votorantim 's controlling stake in Companhia Brasileira de Alumínio (CBA), for approximately 4.69 billion Brazilian reais, equivalent to about USD 900 million at the time of the announcement.
The deal, announced on 29 January 2026, provides for the acquisition of 68.596% of CBA’s share capital and voting rights, one of Brazil’s leading integrated aluminium producers.
The transaction is one of the largest acquisitions in Brazil’s aluminium industry in the past 15 years and marks Chalco’s significant entry into the Latin American market through the acquisition of an integrated industrial producer.
Beyond its economic scale, the deal is of particular legal interest because it combines an international joint venture, the acquisition of control of a listed company, regulatory approvals in several jurisdictions and a subsequent mandatory tender offer.
A joint venture with a Chinese majority stake
The structure provides for the creation of a joint venture in which Chalco will hold a 67% stake and Rio Tinto 33%.
Through this vehicle, the two companies will acquire the stake in CBA currently controlled by Votorantim.
The agreement sets a base price of 10.50 reais per share, equivalent to a premium of approximately 21.2% over the weighted average trading price during the reference period before the announcement.
The price is subject to certain contractual adjustments.
The new corporate structure will combine Chalco’s capabilities across the aluminium value chain with Rio Tinto’s international experience in mining, processing and commodity marketing.
From a corporate governance perspective, the model involves a majority Chinese investment in a Brazilian industrial platform, alongside an international partner with a significant minority stake.
The joint venture’s internal agreements will be important in determining decision-making powers, the financing of future investments and the allocation of responsibilities between the two groups.
Companhia Brasileira de Alumínio, listed on Brazil’s B3 stock exchange, operates an integrated industrial chain encompassing bauxite mining, alumina production, smelting, recycling and aluminium processing.
The company has three producing bauxite mines, with output of approximately two million tonnes a year.
Its industrial complex in São Paulo includes alumina refining, smelting and processed materials production facilities.
The acquisition also has a significant energy dimension.
CBA has an electricity generation portfolio of approximately 1.6 GW, comprising hydroelectric and wind power facilities.
According to information disclosed by Rio Tinto, CBA’s operations use electricity from renewable sources, a feature that is strategically important for lower-carbon aluminium production.
The integration of mining, industrial processing and renewable generation makes CBA a particularly attractive asset for groups seeking to expand their presence in strategic materials production.
CADE approves acquisition without conditions
A significant milestone in the deal process came on 11 March 2026, when the General Superintendence of the Conselho Administrativo de Defesa Econômica (CADE) approved Chalco and Rio Tinto’s acquisition of control of CBA without conditions.
The decision marks significant progress in the regulatory approval process.
However, Brazilian competition approval alone does not mean the acquisition has closed.
The deal also requires competition approvals in other jurisdictions, including China, Germany, South Korea and Uruguay, as well as permits from Brazilian electricity-sector authorities and Chinese regulatory approvals.
This range of jurisdictions creates challenges common to global M&A deals: coordinating regulatory timetables, information obligations, cooperation commitments between buyers and sellers, and contractual management of execution risk.
I have not found sufficiently documented confirmation that the acquisition has definitively closed in the sources reviewed, so the signed agreement should be distinguished from the effective transfer of control.
A mandatory tender offer after the acquisition
Another of the most significant legal aspects is the obligation to launch a mandatory tender offer for CBA’s remaining shares after the sale closes.
This obligation arises under Brazilian rules applicable to certain changes of control in listed companies.
The future joint venture will have to make the relevant offer once it has completed the acquisition of Votorantim’s stake.
The buyers initially also considered the possibility of making an offer to delist CBA, although that option was left for further assessment.
From a legal perspective, the deal requires coordination of the purchase of the controlling stake with minority shareholder protections and Brazilian securities market regulation.
The firms advising Chalco, Rio Tinto and Votorantim
The deal has brought together legal teams from several international and Brazilian firms, with expertise in M&A, capital markets, competition and sector regulation.
Chalco: Mayer Brown, Tauil & Chequer and King & Wood Mallesons
Mayer Brown and Tauil & Chequer Advogados, Mayer Brown’s associated firm in Brazil, advised Chalco on the acquisition.
The Brazilian team was led by Bruno Werneck, a partner in Corporate & Securities, and associate Julio Barboza.
Partners Aline Fidelis, Débora Yanasse and Rodolfo Tellaalso took part, alongside professionals from various practice areas.
The advice included tax partner Giampaolo Marzulli and real estate partner Ludmila Arruda Braga, reflecting the multidisciplinary nature of the deal.
International firm King & Wood Mallesons also advised the Chinese group, with George Zhao and Alice Shenamong the team.
Coordination between Brazilian and international teams is particularly important in a transaction involving the formation of a joint venture and the acquisition of a controlling stake in a listed company.
Rio Tinto: Machado Meyer and Linklaters
Machado Meyer Advogados advised Rio Tinto in Brazil.
The team was led by partners Guilherme Malouf and Liliam Yoshikawa, with specialists from various practice areas related to the deal also involved.
The partners identified include Ana Karina Souza, Celso Costa, Clarissa Figueiredo de Souza Freitas, Diana Pacifico Henne, Luiz Eduardo Miranda Rosa and Martina Zajakoff Predtechensky.
International firm Linklaters also advised Rio Tinto, through a team that included George Casey, Vinita Sithapathy, Rebecca Iles and Caroline Aguiar.
The deal highlights the need to coordinate local and cross-border advice in acquisitions of industrial assets subject to regulatory oversight in multiple markets.
Votorantim: Stocche Forbes and Cleary Gottlieb
On the seller’s side, Votorantimreceived Brazilian legal advice from Stocche Forbes Advogados.
The team included partners André Stocche, Rafael Andrade, Luciana Stracieri, Alessandra Zequi, Ricardo Freoa and Ana Paula Paschoalini, alongside associates Luis Filipe Ferreira da Costa and Thomás Felipe Crosta.
International firm Cleary Gottlieb Steen & Hamilton also represented Votorantim.
Partner Juan Giráldez advised on M&A, while Dan Culley and Cunzhen Huang, together with associate Yiming Sun, worked on competition matters.
Votorantim’s in-house legal team included Glaisy Peres Domingues and Caio Maron Zanini.
The teams involved illustrate the complexity of a deal combining a share sale, competition law, securities market regulation, tax and strategic industrial assets.
Legal implications for China-Brazil M&A
The acquisition of CBA is an example of the ways Chinese groups are expanding in Latin America through large-scale corporate investments.
The deal has five particularly significant dimensions.
Corporate governance of international joint ventures. Chalco’s majority stake and Rio Tinto’s position as a minority partner make the design of governance agreements, reserved matters and dispute resolution mechanisms particularly important.
Merger control in multiple jurisdictions. Securing approvals in different markets requires coordinated legal planning and a precise allocation of regulatory risk.
Capital markets and minority shareholder protection. The acquisition of a listed company triggers obligations under Brazilian rules for certain changes of control, including a future mandatory tender offer.
Mining and energy regulation. CBA’s assets span mining, industrial processing and electricity generation, requiring advice on several regulatory regimes.
Sustainability and industrial competitiveness. The use of renewable electricity in aluminium production adds a commercial and regulatory dimension related to decarbonisation and the environmental requirements of international markets.
China and Brazil deepen industrial integration
The deal between Chalco, Rio Tinto and Votorantim reflects a broader trend of Chinese capital expanding into Latin American assets linked to natural resources and strategic industrial supply chains.
Brazil is an attractive market because of its mineral reserves, manufacturing capacity, energy infrastructure and economic scale.
For Chinese groups, acquiring integrated companies provides simultaneous access to natural resources, processing capacity and consumer markets.
In this context, the agreement concerning CBA is one of the most significant deals announced in 2026 in the Latin American aluminium industry.
For law firms, it also illustrates the sophistication of M&A between China and Latin America, where international legal coordination is critical to structuring investments, securing approvals and completing changes of corporate control.
Key facts
Buyers: Aluminum Corporation of China Limited (Chalco) and Rio Tinto
Seller: Votorantim
Target: Companhia Brasileira de Alumínio (CBA), listed in Brazil
Value: Approximately 4.69 billion Brazilian reais, or about USD 900 million at the time of the announcement
Stake acquired: 68.596% of CBA’s share capital and voting rights
Joint venture: Chalco will hold 67% and Rio Tinto 33%
Regulatory approval: CADE approved the deal without conditions in March 2026
Mandatory tender offer: The buyers must make an offer for the remaining shares after closing, in accordance with the applicable rules
Chalco’s advisers: Mayer Brown, Tauil & Chequer and King & Wood Mallesons
Rio Tinto’s advisers: Machado Meyer and Linklaters
Votorantim’s advisers: Stocche Forbes and Cleary Gottlieb
In-house legal team: Glaisy Peres Domingues and Caio Maron Zanini, of Votorantim
Status: Agreement announced and Brazilian competition approval confirmed; definitive closing pending independent verification